Gogoro posts five-quarter cash-flow streak as margins recover

Gogoro (Nasdaq: GGR), the Taiwan-based operator of the world's largest electric two-wheeler battery-swapping network, has reported second-quarter 2026 revenue of $70.6 million, up 7.3% year-on-year, while gross margin recovered to 22.6% from just 0.3% in the same period a year earlier. The company recorded its fifth consecutive quarter of positive operating cash flow, with first-half inflows of $26.0 million, up more than 70% on the prior-year period.
Net loss narrowed to $4.9 million from $26.5 million in Q2 2025, a $21.6 million improvement the company attributes to the completion of a costly battery upgrade programme, higher production volumes absorbing fixed overhead, and reduced depreciation and operating costs across its installed swap-station base. Adjusted EBITDA (earnings before interest, tax, depreciation and amortisation, excluding share-based compensation and one-off charges) rose to $19.3 million from $12.5 million a year earlier.
The numbers
Battery-swapping service revenue, which accounts for just over half of total sales, was broadly flat at $37.4 million as a higher proportion of entry-level vehicles dampened average revenue per subscriber. The company ended the quarter with 677,000 subscribers, up 4% year-on-year. Hardware revenue grew faster, rising 17.8% to $33.2 million, driven by a 50.8% jump in Gogoro-branded scooter registrations and a bulk delivery to WeMo, a scooter-sharing partner. Market share in Taiwan rebounded to 6% from 2% earlier in the year, helped by new model launches including the EZZY 500 and Gogoro Luna.
Full-year 2026 revenue guidance is held at $285 million to $305 million, a modest recovery from 2025 levels. The company expects its battery-swapping network to reach non-IFRS profitability this year, with the hardware segment following by 2028. Cash on hand stood at $68.8 million at 30 June, including a $16.7 million equity injection from major shareholder Gold Sino.
Chief executive Henry Chiang said the results reflect "measurable improvements in operational efficiency" and that the company's "strongest chapters of 2026 are still ahead."
Market context
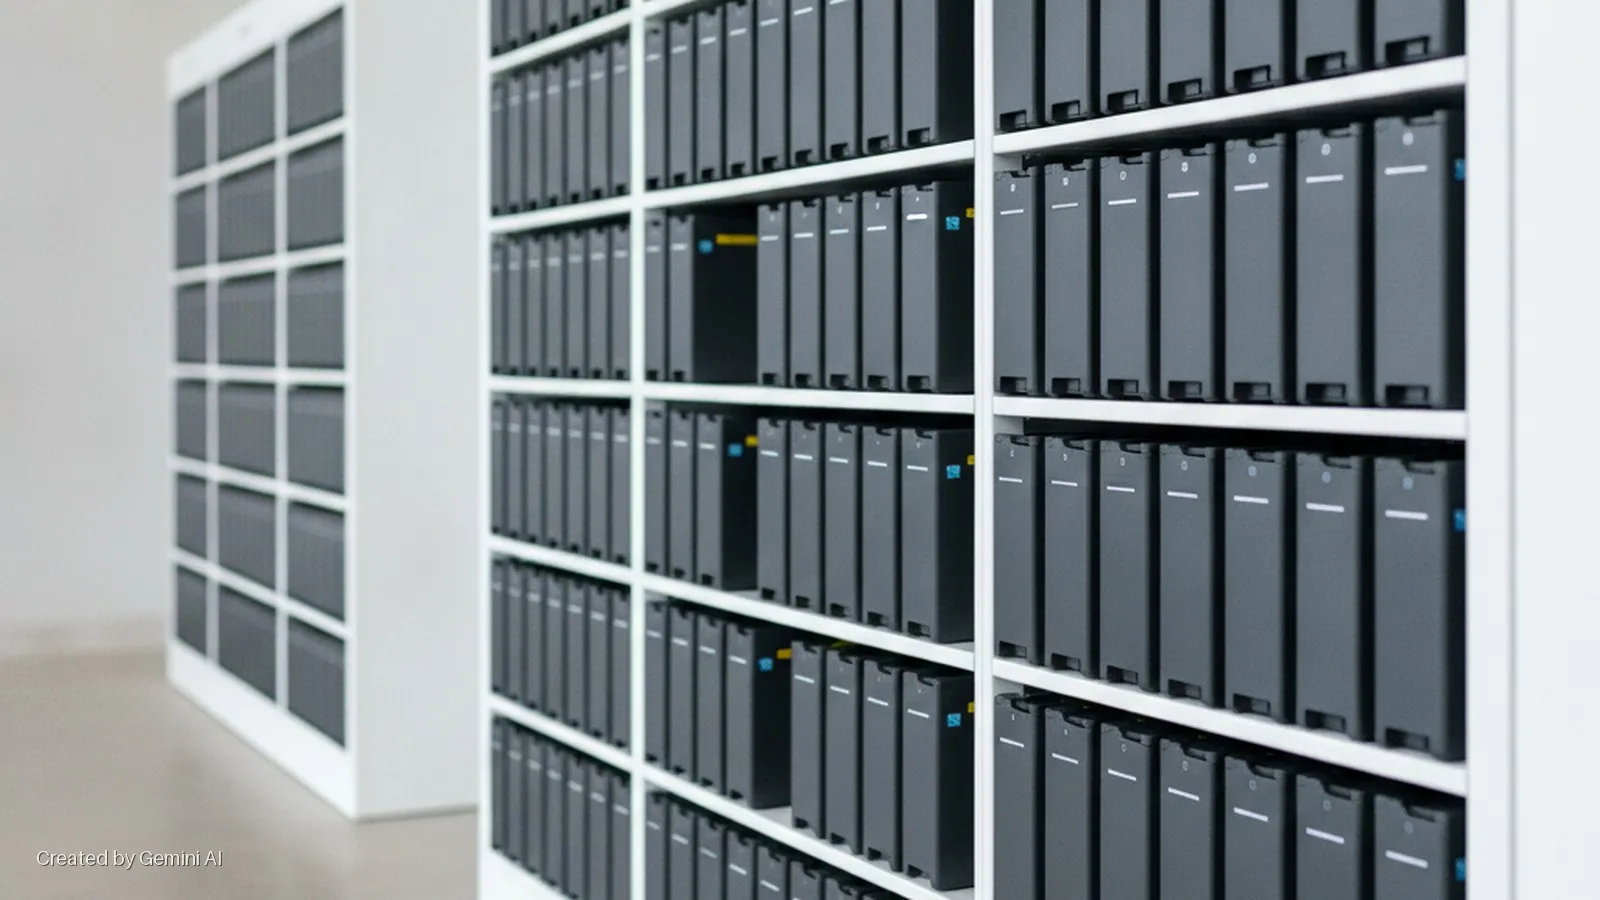
Gogoro operates in a niche it largely created: a city-scale, subscription-based battery-swapping infrastructure for electric powered two-wheelers (ePTWs). The model differs structurally from the direct-sale battery model dominant in most EV markets: subscribers pay a monthly fee for unlimited swaps across more than 2,700 GoStation locations in Taiwan, locking in recurring revenue and allowing Gogoro to manage battery ageing centrally.
Battery swapping has attracted renewed interest beyond two-wheelers. Several Chinese EV manufacturers and a handful of European startups are exploring swap-based passenger-car models, though high standardisation costs and thin vehicle volumes have slowed progress. In the two-wheeler segment, Gogoro's closest comparable deployments are in India and Southeast Asia, where the economics of swapping are compelling given low per-capita vehicle costs and dense urban ride patterns.
The company's capital position carries some constraints. Total debt stood at roughly $331 million at 30 June against $68.8 million in cash, and equity financing has relied on a commitment from a director linked to its largest shareholder rather than the public markets. Capital expenditure has fallen sharply following the battery upgrade completion, which gives near-term cash headroom, but the hardware profitability target of 2028 requires sustained subscriber and scooter-volume growth in a market where Gogoro is rebuilding share after a period of sharp losses.
For investors tracking the low-carbon mobility space, the Q2 results offer evidence that the swapping-as-a-service model can generate operating cash at meaningful subscriber scale, even if a path to net profitability on an IFRS basis remains some distance away. The Q3 community event and further product launches are the near-term catalysts the company is positioning as proof points for its multi-year recovery thesis.